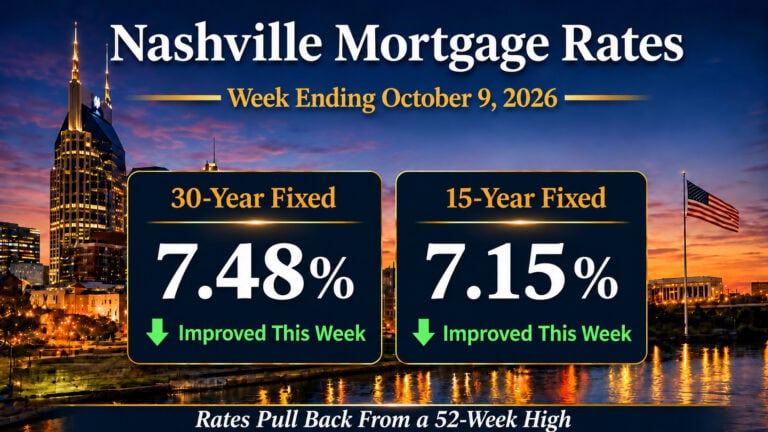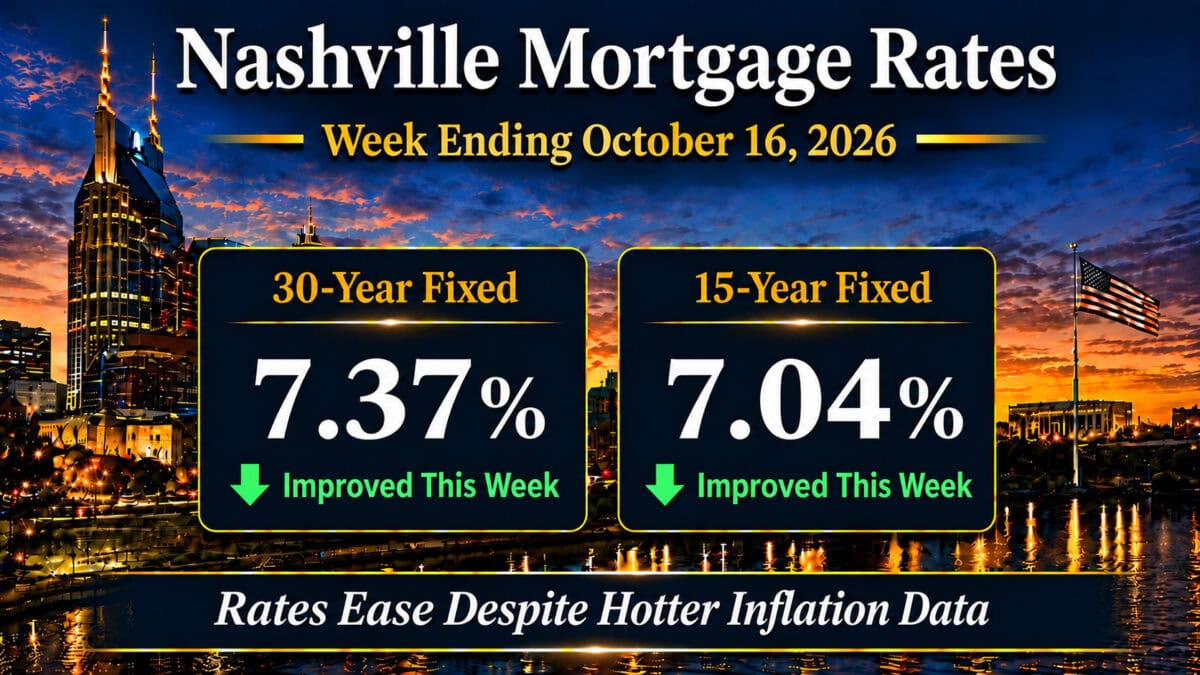
Nashville mortgage rates closed the week ending October 16, 2026 at 7.37% on the 30-year fixed. That is down 11 basis points from the previous Friday’s 7.48%. The 15-year fixed finished at 7.04%, also down 11 basis points. FHA 30-year financing sits near 6.99%.
The surprise this week is that rates fell at all. September inflation came in hotter than expected on both the CPI and PPI reports, with consumer prices up 0.6% for the month and core prices up 0.3%. That usually pushes rates higher. This time, however, bond buyers stepped in anyway.
I distrust a rally that arrives on bad news. So let me be plain about where this one came from. It came from fear in the stock market, not from any improvement in inflation. The buying was real, but it lasts only as long as that fear does.
Freddie Mac’s survey held at 7.40% Thursday, unchanged on the week and still the top of its own 52-week range. The survey window closed before Thursday’s move. Two instruments, one week, both correct, and the daily index is the one carrying the newer information.
In this report
Nashville Mortgage Rate Summary for the Week Ending October 16, 2026
- 30-year fixed: 7.37%, down 11 basis points from 7.48% the previous Friday (Mortgage News Daily daily index, October 16, 2026).
- 15-year fixed: 7.04%, down 11 basis points from 7.15% the previous Friday (Mortgage News Daily, October 16, 2026).
- FHA 30-year: 6.99% (Mortgage News Daily, October 16, 2026). On a condo the building has to be FHA approved too.
- Jumbo 30-year: 7.67% (Mortgage News Daily, October 16, 2026). In the 5 buildings on my luxury high-rise list, average sales run above $1.25 million, so a 20%-down loan there is a jumbo.
- Freddie Mac PMMS 30-year: 7.40%, unchanged from 7.40% (survey week ending October 15, 2026). A year ago the same survey read 6.27%, so the 30-year is 113 basis points higher than it was on October 16, 2025.
- Freddie Mac PMMS 15-year: 6.71%, down 2 basis points from 6.73% (October 15, 2026). A year ago, 5.52%, so 119 basis points higher.
- 10-year Treasury: 5.09%, down 15 basis points from 5.24% the previous Friday (U.S. Treasury daily par yield curve, October 16, 2026). The week’s high was 5.21% on October 13.
Freddie Mac publishes every Thursday at noon Eastern: Primary Mortgage Market Survey.
Mortgage Rate Dashboard
The mortgage rate dashboard shows a 7.37% 30-year fixed rate, a 7.04% 15-year fixed rate, an FHA 30-year rate near 6.99%, a 10-year Treasury yield near 5.09%, and a mortgage spread near 2.28%, as of the week ending October 16, 2026. That spread is the same-Friday basis: the Mortgage News Daily index less the Treasury yield. Both legs are dated October 16, 2026.
What Happened to Nashville Mortgage Rates This Week
A 4-day week that turned on Wednesday afternoon
Bond markets were closed Monday, October 12 for Columbus Day, so the week started Tuesday at 7.46%. Wednesday brought September CPI and the index eased a single basis point to 7.45%. The real story was the reversal inside the day, not the close. Thursday the index fell 12 basis points to 7.33%. Mortgage News Daily called it the biggest one-day drop in at least 3 months, and it was the lowest close since September 23. Friday’s close of 7.37% sits 24 basis points below the October 5 close of 7.61%, the top of the index’s 52-week range.
Friday gave 4 basis points back
The index closed the week at 7.37%, 4 basis points above Thursday’s low. I pay attention to that kind of Friday. Stocks fell again and bonds did not benefit this time. That is the first sign this rally’s bid has a limit. One day proves nothing. But after a run this sharp, it is the day I would want repeated before I called a trend.
Institutional Macro Snapshot
What Moved Mortgage Rates This Week
September inflation ran hot and rates fell anyway
September CPI landed Wednesday, October 14. Headline prices rose 0.6% in the month and 3.7% over 12 months. Core prices, which strip out food and energy, rose 0.3% and 2.6%. Both came in above forecast, and the core strength was broad rather than confined to fuel. PPI on Thursday also printed above expectations. On the ordinary rules of this market, that combination raises rates.
It did, briefly. The 10-year Treasury jumped on the release, then closed the day at 5.19%, below Tuesday’s 5.21%. That round trip sums up the week.
The bid came from the stock market, not from the data
Two things did the work. Worries about an AI-related pullback moved money out of equities and into bonds. The fear is that trouble at individual AI infrastructure borrowers spreads to their lenders. Yields had also reached levels investors were waiting for. Buyers who had sat out finally had a reason to step in. Mortgage News Daily credits both, in that order.
Here is the gap I want you to see. A rally driven by an inflation surprise has a cause you can watch repeat on a published calendar. A rally driven by equity fear has no schedule, and it reverses the moment the fear does. I treat this week’s improvement as real, and as easier to reverse than one built on better inflation data.
The Fed meets October 27 and 28 with no new projections
The target range has been 3.75% to 4.00% since the increase at the September 15-16 meeting. Those minutes were released October 7. The next scheduled FOMC meeting is October 27-28, 2026, and it does not carry a Summary of Economic Projections. The December 8-9 meeting does. Futures traders now see another increase as unlikely. CME FedWatch put the odds of a hike at the October meeting at 15.5% on October 16, 2026. A week earlier they were 17.7%, and a month earlier 55.4%. Fed commentary this week leaned toward the view that policy is already restrictive enough. For long rates, that matters more than any single inflation print.
The 10-Year Treasury and the Mortgage Spread
The 10-year closed Friday at 5.09%, down 15 basis points from 5.24% the previous Friday. Tuesday’s high was 5.21%. Against the 30-year index at 7.37%, the same-Friday mortgage spread is 228 basis points. That is 4 wider than last week’s 224.
Nashville mortgage rates did not keep pace with the Treasury rally. That is normal in a fast move: the benchmark turns first and lenders follow over days. The survey basis is the one that compares to the long-run average. On it, the spread settled the week before at 214 basis points, for the week ending October 9, 2026. That is Freddie Mac’s 7.40% less the 5.26% weekly average 10-year yield. Since Freddie Mac changed the PMMS methodology in November 2022, that spread has averaged about 246 basis points. That settled figure for the week ending October 16 publishes Monday, October 19. The spread is not what is hurting you. The Treasury yield is.
What Nashville Mortgage Rates Cost a Buyer Right Now
Here is what this week’s Nashville mortgage rates cost in principal and interest only, on a 30-year fixed at 7.37%. Taxes, insurance and any HOA dues sit on top of these figures.
| Loan amount | Monthly P&I at 7.37% |
|---|---|
| $300,000 | $2,071 |
| $400,000 | $2,761 |
| $500,000 | $3,452 |
| $600,000 | $4,142 |
| $750,000 | $5,178 |
A $500,000 purchase with 20% down runs $2,761 a month. A $1,000,000 purchase with 20% down runs $5,523. This week’s 11-basis-point improvement is worth $30 a month on that $400,000 loan, down from $2,791 last Friday. I call that real, and smaller than the headlines about the week suggest. A half-point move is worth about $34 per $100,000 borrowed. The East Nashville pricing tiers show how far one neighborhood spans those rows.
The 15-year costs more monthly and far less in total
On the same $400,000 loan the 15-year runs $3,604 against $2,761, a difference of $843 a month. Lifetime interest is $248,768 against $594,082, a saving of $345,314. But the rate gap between the terms is only 0.33%. You are buying that saving with payment, not with a discount. At a gap this narrow I would rather see the cash in reserves.
What I Would Do With a File Right Now
What should Nashville agents tell buyers about this week’s rates?
You probably got 3 times the usual number of lender emails about Nashville mortgage rates this week. I treat that as a sentiment indicator, not a rate quote. Here is the number to give your client instead. The 30-year index fell 11 basis points, from 7.48% to 7.37%. On a $400,000 loan that is $30 a month. Worth a phone call. Not worth rewriting an offer over.
The useful version of this week for a listing appointment is the buydown math below, not the rate itself. A seller credit moves a buyer’s first-year payment further than 11 basis points does, and I would lead with that.
The lock call this week
If you are closing inside 30 days, take the improvement. This rally rests on equity fear and nothing else, and the week’s own Friday showed that support thinning. Floating here means betting that the stock market stays frightened, which is not a thesis I would hand a client. If you are 60 days or further out, float with a float-down. Watch 5.20% on the 10-year: back above it and this week unwinds.
Ask the seller for a 2-1 buydown before you ask for a price cut. On a $500,000 loan at 7.37%, full payment is $3,452. Year one at 5.37% is $2,798, year two at 6.37% is $3,118. Total relief is $11,848, funded by a seller credit. I have closed 550-plus short-term rental transactions, and sellers are more than happy to do a buydown. Most would rather do that than cut the price, because the sale price they worked for stays on the books. Same money to them, a much bigger first-year difference to you. On an income property, DSCR financing qualifies off the property rather than off your returns.
On a refinance, run the break-even on today’s quote. Rates are 113 basis points above last October. Most files written this year are not refinance candidates yet. If yours clears break-even inside 24 months at 7.37%, take it. Take the free re-lock too, if your lender offers one.
What I Am Watching Next
Next week is light on top-tier data ahead of the Fed. Housing carries the calendar: September housing starts, building permits and pending home sales all land Tuesday, October 20, plus the weekly jobless claims on Thursday. With rates near the highest levels of 2026, further softening in housing would help bonds rather than hurt them. My Nashville housing market outlook covers what that means locally.
The level I am watching is 5.20% on the 10-year Treasury. Yields topped out at a 5.31% close on October 5, then dropped under 5.20% mid-week. The question now is whether that level holds as a ceiling on the way back up. If it does, 5.00% is reachable. On the mortgage side, a close below Thursday’s 7.33% would be the first genuine lower low of this run. A move back above the previous Friday’s 7.48% would say the rally is done. I update the weekly rate tracker every Friday.
Nashville Mortgage Rates FAQ
What is the current 30-year mortgage rate in Nashville?
The 30-year fixed rate was 7.37% on October 16, 2026, per the Mortgage News Daily daily rate index. Freddie Mac’s Primary Mortgage Market Survey, released October 15, 2026, put the national 30-year average at 7.40%.
Did Nashville mortgage rates go up or down this week?
Down. The Mortgage News Daily 30-year index fell 11 basis points, from 7.48% on October 9, 2026 to 7.37% on October 16, 2026. The week’s low was 7.33% on October 15.
How much higher are mortgage rates than a year ago?
113 basis points on the 30-year. Freddie Mac’s survey read 6.27% on October 16, 2025 and 7.40% on October 15, 2026. The 15-year is 119 basis points higher, 5.52% to 6.71%.
What is the monthly payment on a $400,000 mortgage right now?
$2,761 in principal and interest on a 30-year fixed at 7.37%, the Mortgage News Daily index rate for October 16, 2026. That is $30 a month less than the $2,791 the same loan cost at 7.48% on October 9, 2026. Taxes, insurance and any HOA dues are extra.
What is the mortgage spread over the 10-year Treasury?
228 basis points on October 16, 2026: the 7.37% 30-year index less the 5.09% 10-year Treasury, both dated that Friday. On Freddie Mac’s survey basis, the spread settled the week before at 214 basis points for the week ending October 9, 2026, which is 7.40% less a 5.26% weekly average yield. The post-2022 average on that basis is about 246 basis points.
Why did mortgage rates fall when inflation came in hot?
Because the bid came from equities, not from the data. September core CPI rose 0.3% in the month and 2.6% over 12 months, reported October 14, 2026. That was above forecast, yet the 30-year index still fell 11 basis points on the week, to 7.37%. Mortgage News Daily ties the move to investors leaving stocks over AI-related credit worries, and to buyers stepping in once yields reached levels they had been waiting for.
Sources
- Mortgage News Daily rate index and Rate Watch, October 16, 2026
- Freddie Mac PMMS, October 15, 2026
- U.S. Treasury daily yields, Fed H.15 and FRED WGS10YR
- BLS September CPI, October 14, 2026
- FOMC calendar and CME FedWatch, October 16, 2026
Rates are the Mortgage News Daily index for October 16, 2026 and Freddie Mac’s survey for the week ending October 15, 2026. They are national figures, not a quote. Mortgage rates change daily, and yours depends on credit, loan size, property type, occupancy and lock period. Payments are principal and interest only. Nothing here is a commitment to lend or investment advice, and forward-looking views are the BDG Partners team’s as of October 16, 2026. Broker fees are not set by law and are fully negotiable.
About the Broker
I am Grant Hammond, a Tennessee-licensed broker (#261980) with BDG Partners at Compass RE in Nashville. For 25 years I have worked in the Middle Tennessee market, with over $1 billion in career sales and 350-plus closed high-rise condo transactions. Every Friday I publish this rate report.
Want my read on a specific file, a lock decision or a buydown structure? Reach out and I will run the numbers with you.